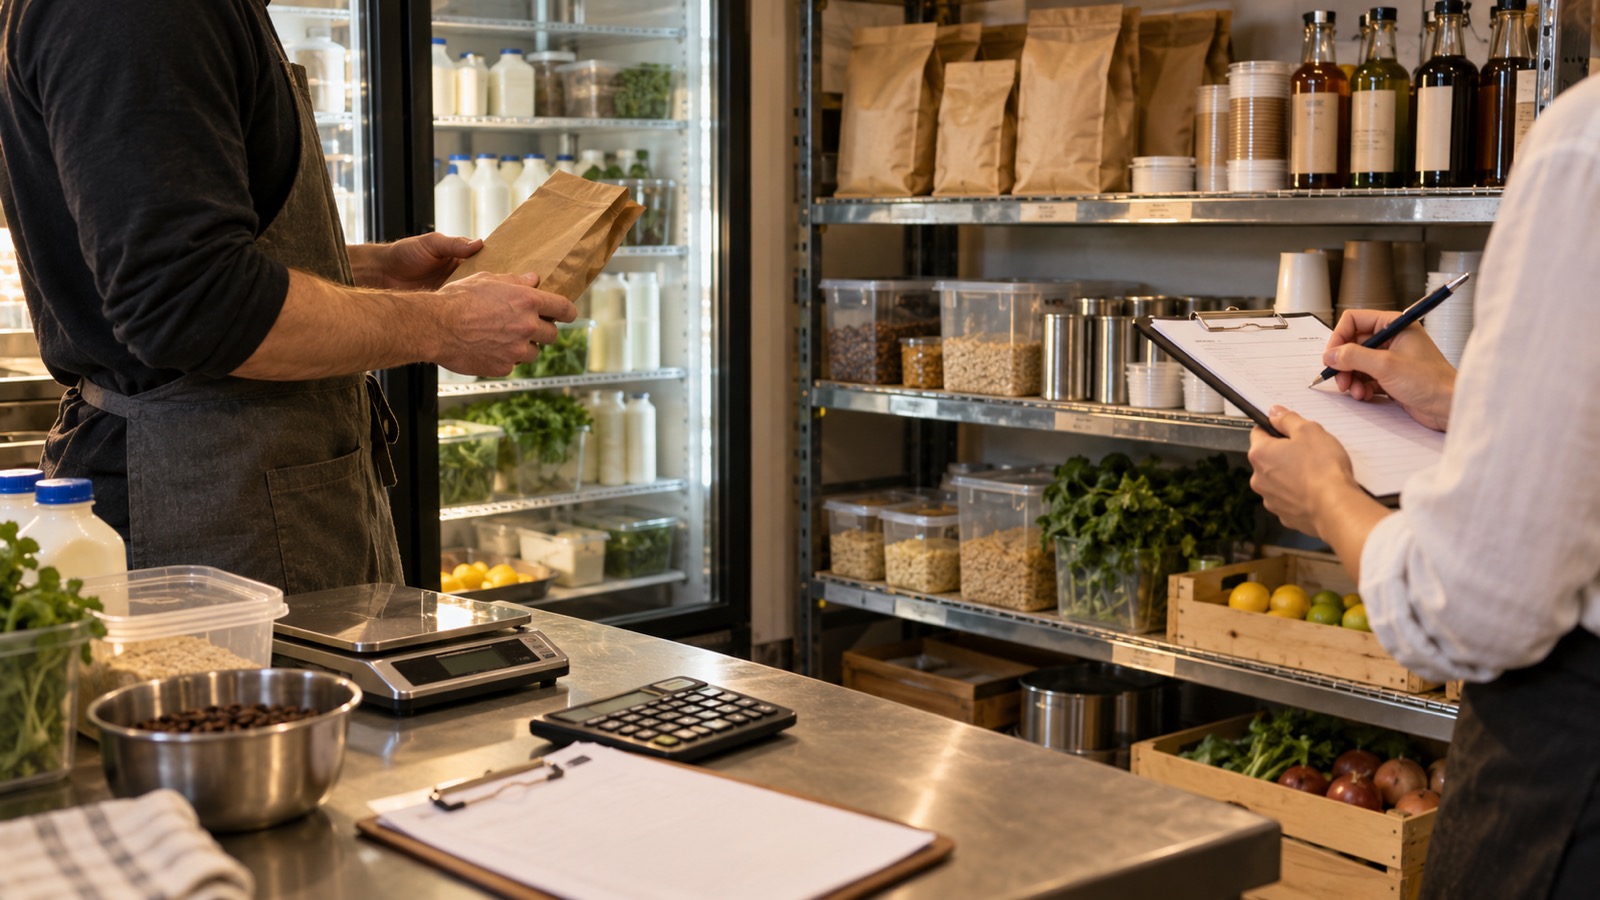
Stock at settlement should be an agreed, evidenced adjustment—not a last-minute estimate copied from the seller’s accounts. Before signing, a café buyer should define which items qualify, how each category will be counted and valued, when the count occurs, who participates and how disagreements will be resolved.
The final number matters, but so does what sits behind it. Stock that is expired, unsafe, opened without a reliable remaining life, owned by a supplier or excessive for normal trading may have little or no value to the buyer. A disciplined joint count turns an ambiguous handover into a traceable settlement calculation.
Define “stock” before the count
The sale agreement should separate inventory intended for resale or use in producing sales from other things found on the premises. A café stock schedule may include coffee beans, tea, packaged drinks, milk, food ingredients, retail merchandise, disposable packaging and selected cleaning consumables. It should state whether it includes opened containers, pre-prepared food, frozen batches, alcohol, branded packaging, uniforms, spare parts or office supplies.
Keep stock distinct from plant and equipment, prepaid expenses, deposits and customer obligations. Crockery, utensils, small appliances and reusable containers usually need an asset treatment rather than a per-unit stock adjustment. Gift cards and prepaid catering orders are liabilities or performance obligations to investigate, not inventory simply because cash was received.
Set exclusions clearly. Typical candidates are:
- items past their use-by date, damaged or contaminated;
- stock with missing identification or unverifiable storage history;
- opened goods that cannot be safely or commercially used;
- obsolete menus, old branded packaging or goods the buyer will not sell;
- quantities above an agreed normal operating level; and
- consignment or supplier-owned items unless ownership and transfer are documented.
Also agree whether the stock adjustment is capped. A cap can stop the seller increasing purchases before settlement and requiring the buyer to fund inventory it did not request. It does not replace the count; it defines the buyer’s maximum exposure.
Prepare the café for a reliable joint stocktake
Ask the seller to provide an inventory list several days beforehand, grouped by physical location and category. It should show product description, pack size, unit of measure, quantity, purchase price, supplier, invoice date, batch or date mark where relevant, and whether the package is open. Obtain recent supplier invoices and credit notes so prices can be tested.
Agree operational cut-off procedures. Record the last supplier deliveries, transfers, wastage entries and sales before the count. Keep delivery dockets for anything arriving during the process. If the café trades between counting and settlement, identify how consumption and purchases will be rolled forward. Otherwise, the parties may count the same carton twice or omit goods used after one room was counted.
The premises should be organised without concealing condition: like items together, shelves accessible, cool rooms lit and open containers visible. Avoid accepting a spreadsheet prepared from the perpetual inventory system without physical verification. The ATO says stocktake records should record stock descriptions and values, who performed the count, how and when it occurred, and the valuation method used (ATO). Its determination on stocktakes also notes that guessing or relying on an earlier count is not sufficient for arriving at an accurate year-end value (ATO). Although settlement is a contractual event rather than necessarily an income-year stocktake, the same evidence discipline is useful.
Count quantities, units and usable yield
The buyer and seller, or their nominated representatives, should attend the count and sign the same numbered sheets. Work systematically through dry storage, refrigerators, freezers, display areas, bar, retail shelves and any off-site storage. Mark each area complete and prohibit unrecorded movement between counted and uncounted zones.
Count sealed units by verified pack size. Weigh bulk goods such as coffee beans or flour, deduct container weight and state the measurement basis. For opened bottles, use a documented percentage or weight method consistently rather than a visual guess. Prepared sauces, batters or frozen batches require a recipe yield and a defensible remaining life; a tray labelled “soup” is not a reliable quantity or quality record.
Use the supplier’s unit and the count unit carefully. Six cartons are not six bottles, and a case price cannot be applied to each individual unit. Photograph material or disputed lines, date marks and damaged packaging. Record zero quantities rather than deleting expected items, which preserves the audit trail.
Test condition, expiry and ownership
A count proves presence, not value. Inspect packaging integrity, pest or moisture damage, freezer burn, temperature records and storage conditions. FSANZ says food businesses must keep food safe and suitable, including protecting it from contamination and storing potentially hazardous food at 5°C or colder unless another safe control is demonstrated (FSANZ). Stock should not be given full value if the buyer cannot establish that required storage controls were maintained.
Date marks need line-by-line treatment. FSANZ explains that food cannot legally be sold after its use-by date because of health or safety risk, while food past a best-before date may be sold only if it remains fit for human consumption, despite possible quality loss (FSANZ). The agreement should say whether short-dated but usable goods receive full value, a discount or no value. Use objective thresholds by category rather than debating each yoghurt at settlement.
Verify ownership against invoices and supply arrangements. Coffee, syrups, gas cylinders, display stock or promotional goods may be loaned, supplied on consignment or subject to return terms. Exclude goods the seller cannot transfer, or obtain written supplier confirmation of the buyer’s rights and obligations.
Agree a valuation basis and settlement adjustment
The contract should state the valuation rule in operational terms. Common approaches include verified recent invoice cost, replacement cost under the buyer’s continuing supplier terms, or a negotiated percentage for opened and short-dated stock. Do not mix methods opportunistically by line. Deal expressly with rebates, freight, discounts, credits and GST, and state whether values are GST-inclusive or GST-exclusive.
Tax accounting concepts do not automatically decide the contractual price. The ATO’s general trading-stock guidance recognises cost, market selling value and replacement value for income-tax purposes, but the buyer and seller still need a sale-agreement method that fits this transaction. Likewise, the GST treatment of the wider acquisition depends on its facts: the ATO says a sale of a going concern is GST-free only when the applicable conditions are met, including a written agreement and supply of everything necessary for continued operation (ATO). The parties’ accountants and lawyers should confirm the stock adjustment, purchase-price allocation, invoice and GST treatment together.
Hypothetical example: the joint count identifies $18,400 at recent invoice cost. The agreed rules exclude $900 of supplier-owned goods and $600 past use-by, discount $2,000 of short-dated stock by 40%, and cap payable stock at $15,000. The calculated value is $16,100, so the contractual adjustment is $15,000 because of the cap. This illustrates mechanics only; it is not a valuation benchmark.
Build in sign-off and dispute controls
The signed count should show each adjustment and attach the supporting invoices, photos and calculations. Specify when the final schedule is delivered, how long each party has to object, and whether undisputed amounts settle immediately. For unresolved lines, nominate an independent accountant or stocktaker, define who pays and state whether the expert’s decision is final within an agreed tolerance.
Before authorising settlement, confirm:
- every counted line falls within the agreed stock definition;
- ownership, quantity, unit and invoice price can be traced;
- expiry, condition and storage exceptions are recorded;
- pre- and post-count movements reconcile to the cut-off;
- GST, discounts, credits and the cap are applied consistently; and
- both parties have signed the same final schedule.
This is a coordination exercise between commercial evidence and the sale agreement. The buyer’s lawyer should settle the contractual mechanism and ownership issues; the accountant should review valuation, allocation and tax treatment; and a food-safety specialist may be needed where storage history or suitability is uncertain.
Related reading
- Café acquisitions
- Buying a Café in Australia: A Buyer’s Guide
- Food Costs, Waste and Menu Margins: What Café Buyers Should Investigate
- Supplier Accounts, Contracts and Continuity When Taking Over a Café
- Gift Cards, Deposits and Prepaid Orders: Obligations to Investigate Before Settlement
Sources
- Stock and asset records — Australian Taxation Office, reviewed 2026-10-03
- TD 93/125 — Australian Taxation Office, reviewed 2026-10-03
- Selling a going concern — Australian Taxation Office, reviewed 2026-10-03
- Storing food safely — Food Standards Australia New Zealand, reviewed 2026-10-03
- Use-by and best-before dates — Food Standards Australia New Zealand, reviewed 2026-10-03
Disclaimer
This article provides general information only. It does not constitute legal, tax, accounting, financial, credit, valuation or other professional advice. Circumstances differ. Obtain advice from appropriately qualified advisers before acting or entering a transaction.